Governor Nandalal Weerasinghe says lower inflation could undermine growth potential; critics warn of currency depreciation, weaker purchasing power and higher borrowing costs
By The Pulseline News Desk
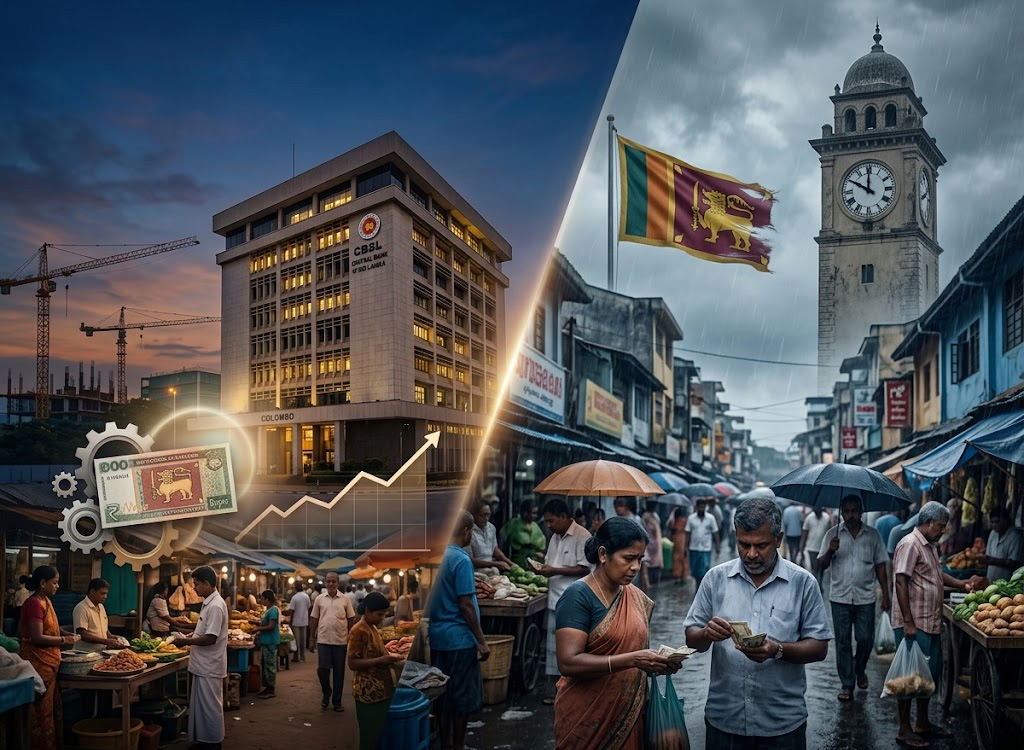
Sri Lanka’s Central Bank (CBSL) has defended its decision to maintain a 5% inflation target through October 2029, rejecting calls from economists and monetary policy critics to lower the benchmark to 2%, amid continuing debate over purchasing power, currency stability and the cost of living.
Central Bank Governor Nandalal Weerasinghe has said the 5% target represented the optimal balance between price stability and economic growth, arguing that a lower target could constrain the economy’s growth potential without necessarily improving overall public welfare.
The Central Bank has recommended the 5% target to the Government, which had agreed to the three-year arrangement. However, critics have argued that maintaining a higher inflation target risks normalising continued price increases, placing pressure on household incomes and potentially contributing to long-term currency depreciation.
The disagreement highlights a broader economic policy question as Sri Lanka recovers from its recent economic crisis, which is whether the country should prioritise a more aggressive reduction in inflation or retain a higher target to accommodate economic expansion.
CBSL rejects calls for 2% target
Speaking at a panel discussion with Central Bank officials, Weerasinghe has said inflation targets should reflect a country’s growth potential and economic circumstances rather than be determined solely by the desire to minimise price increases.
Responding to arguments in favour of a 2% target, he has acknowledged that lower inflation might appear preferable from a purchasing-power perspective but questioned whether it would deliver better economic outcomes.
“So, this is where one can argue, why 2% inflation, is it better? Looking at the purchase power, it looks better, but it’s not better,” he has said.
“It is worse, because it will create a country that can grow, much lower below its potential…. It’s not welfare optimisation. It will make a lot of people worse off than it will make a lot of people better off.”
Weerasinghe has said the Central Bank had conducted extensive research before settling on 5% and had found no compelling evidence that a substantially lower target would produce a better overall outcome.
“I think we don’t see any other counterfactual to say, it’s not 5%, it’s 4%, or 2%, or 3%, or 6%, or 7%,” he has said, adding that a lower inflation target could produce worse results if achieving it required economic growth to fall below the country’s potential.
The Governor has said the target could be reassessed in the future, with any adjustment based on economic data and evidence rather than a predetermined commitment to a lower rate.
Purchasing power at the centre of debate
Economists advocating a 2% target have argued that persistently higher inflation gradually erodes the purchasing power of households, particularly those whose wages do not increase in line with living costs.
At an annual inflation rate of 5%, the general price level would rise by approximately 15.8% over three years if inflation remained at that rate. At 2%, the cumulative increase would be approximately 6.1%.
The difference would be significant for households managing food, housing, transport, healthcare and education expenses, particularly lower- and middle-income families with limited capacity to absorb higher costs.
However, the inflation target does not mean prices will rise by exactly 5% every year. It is a medium-term policy objective, while actual inflation can fluctuate depending on energy prices, food costs, exchange-rate movements, taxation and other economic conditions.
Nor does a lower inflation target automatically guarantee higher real incomes. Its impact on household welfare would depend on how monetary policy affects economic growth, employment, wages, interest rates and the cost of achieving the target.
The Central Bank’s position is that pursuing a lower target at the expense of economic activity could leave some households worse off if slower growth reduces employment and income opportunities.
Critics, meanwhile, have argued that allowing a higher rate of inflation to persist can impose a continuing burden on households when nominal wages fail to keep pace with price increases.
Currency stability and inflation differential
A key argument for lowering the target concerns the relationship between domestic inflation and the exchange rate.
Sri Lanka’s critics of the 5% target point to the approximately 2% inflation objectives maintained by major advanced economies, including the United States (US) and the euro area.
They argue that maintaining a higher inflation target than major trading partners creates a persistent inflation differential that can place downward pressure on the rupee over time.
Under this argument, a 2% target would bring Sri Lanka closer to international inflation benchmarks, strengthen confidence in the domestic currency and reduce the risk of recurring external imbalances.
However, the relationship between inflation and exchange rates is not automatic. Currency movements also depend on productivity, capital flows, foreign-exchange reserves, trade performance, fiscal policy and market expectations.
A lower inflation target alone would therefore not guarantee a stronger rupee or eliminate balance-of-payments pressures.
Nevertheless, proponents of a tighter target contend that stronger price stability could help anchor inflation expectations and reduce the risk of monetary policy accommodating persistent currency weakness.
For an economy that has experienced severe currency depreciation and a sharp inflation shock, the credibility of the monetary framework remains central to rebuilding public confidence.
Interest rates and investment costs
The debate also extends to borrowing costs and private-sector investment.
Critics have argued that a 5% inflation target, combined with an accountability band of two percentage points on either side, leaves room for inflation to fluctuate between 3% and 7%.
They have contended that this range could contribute to uncertainty over future prices, prompting lenders and investors to demand higher nominal returns to compensate for inflation risks.
Such risk premiums can increase borrowing costs for businesses seeking to expand operations, invest in equipment or undertake long-term projects. They can also raise the Government’s debt-servicing costs when financing conditions reflect elevated inflation expectations.
Advocates of a 2% target have argued that a stronger commitment to price stability could eventually lower inflation expectations, improve monetary policy credibility and create a more predictable environment for long-term investment.
However, a lower inflation target would not automatically reduce interest rates. The outcome would depend on inflation expectations, the credibility of the Central Bank, financial-market conditions and the monetary policy measures required to achieve the target.
The Central Bank’s counterargument has been that an excessively restrictive policy stance could suppress economic activity, offsetting any benefits from lower inflation and potentially weakening investment and employment.
Missed targets complicate the debate
The Central Bank’s record in meeting its inflation objective is another point of contention.
Available data indicate that inflation missed the target during most quarters in the three-year period through the end of September 2026, frequently moving outside the accountability range.
The Central Bank has attributed periods of below-target inflation to lower energy prices, while increases in energy costs have contributed to inflation breaching the upper limit.
These fluctuations illustrate the challenges of maintaining price stability in an economy exposed to external commodity-price movements and domestic supply shocks.
They also raise questions about how the Central Bank should assess the effectiveness of its inflation framework and communicate the distinction between temporary price shocks and persistent inflationary pressures.
A target is not a guarantee that inflation will remain at a specified rate in every quarter. Nevertheless, repeated deviations can affect public confidence if households and businesses become uncertain about the medium-term direction of prices.
For critics, the record strengthens the case for reconsidering whether the existing target provides a sufficiently firm anchor for inflation expectations.
For the Central Bank, the challenge is to demonstrate that the 5% objective remains appropriate while improving its ability to bring inflation back within the designated range when external shocks push it off course.
Evidence, not a predetermined target
Weerasinghe has said the Central Bank remained convinced that 5% was the appropriate target, while leaving open the possibility of a lower objective in the future.
He has maintained that any revision would have to be supported by data and evidence demonstrating that a different target would deliver better economic outcomes.
The debate is therefore not simply about whether lower inflation is desirable. It is about the pace at which Sri Lanka should pursue price stability, the economic costs of achieving it and the extent to which a lower target would improve household welfare over the longer term.
As Sri Lanka continues its economic recovery, the effectiveness of the current framework will ultimately be judged not only by the target announced by the Central Bank, but also by its ability to maintain predictable inflation, protect the purchasing power of incomes and support sustainable economic growth.



Leave a comment