By The Pulseline News Desk
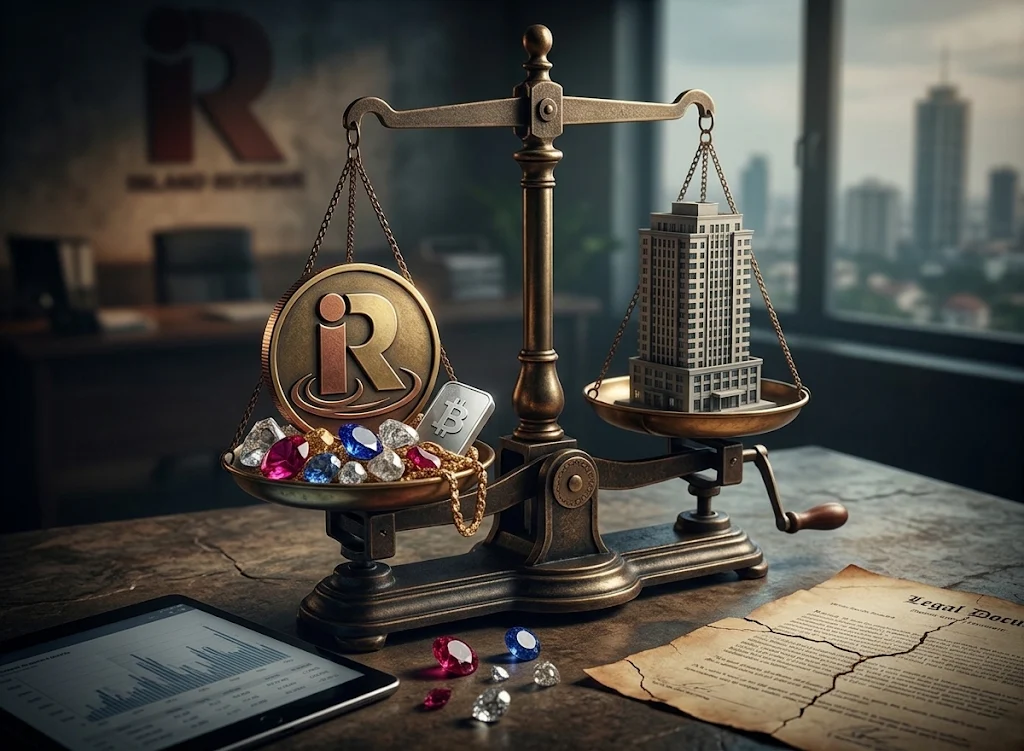
The Inland Revenue Department (IRD) will introduce formal valuation guidelines for cryptocurrencies, broadcasting licences, gems, jewellery and real estate as the Government moves to expand capital gains taxation to digital and intangible assets under the 2027 Budget.
The move is intended to address longstanding uncertainty over how taxable capital gains should be calculated, particularly in the absence of clear valuation rules for assets whose market values can fluctuate significantly or are difficult to establish retrospectively.
Speaking at a post-budget webinar organised by Deloitte Sri Lanka, IRD Senior Deputy Commissioner Nihal Wijewardena has acknowledged that the absence of official valuation guidelines had already resulted in disputes over the market value of assets as at September 30, 2017, the baseline date used for calculating capital gains under the existing tax framework.
Even the valuation of land and buildings has generated disagreements, highlighting the challenges the tax authority could face when assessing digital assets and intangible rights.
Wijewardena has said the forthcoming tax amendment would empower the Commissioner General of Inland Revenue to issue specific valuation guidelines covering different categories of assets.
“Definitely this time the provision will grant power to the Commissioner to issue a specific guideline when the amendment act is in operation,” he has said.
Under the existing framework, capital gains tax primarily applies to the disposal of investment assets such as land, buildings and company shares, with gains generally taxed at 15% for individuals and 30% for companies.
The 2027 Budget proposes expanding the definition of taxable capital assets to include digital and virtual assets, including cryptocurrencies, as well as telecommunications and broadcasting licences, gems, jewellery and precious metals.
The proposed expansion brings a wider range of assets within the capital gains tax framework but also raises questions about how the IRD will establish acquisition costs and market values, particularly for assets that lack transparent trading markets or reliable historical pricing information.
Tax practitioners participating in the discussion have warned that valuing volatile cryptocurrencies and intangible rights could prove considerably more complicated than assessing conventional property. They have stressed the importance of publishing clear valuation methodologies before the new provisions are enforced.
Merger rules and tax avoidance
Meanwhile, the IRD is also preparing anti-avoidance provisions governing corporate amalgamations and mergers, an area that currently lacks specific guidance under Sri Lanka’s tax legislation.
The absence of clear rules has created uncertainty over whether companies involved in mergers can carry forward accumulated business losses and how such transactions should be treated for tax purposes.
Wijewardena has said the department intended to distinguish genuine commercial restructurings from artificial arrangements designed primarily to obtain tax advantages.
He has indicated that legitimate business mergers should be allowed to take place on a tax-neutral basis, while transactions structured principally to absorb accumulated tax losses would face scrutiny.
“If the first reason for the amalgamation is business we can accept, if the first reason is tax avoidance then those should be answered,” he has said.
However, Deloitte panelists have cautioned that the proposed anti-avoidance framework should be developed in consultation with the private sector to ensure that legitimate corporate restructurings are not inadvertently discouraged.
VAT refunds remain a key accountability test
Wijewardena has also identified the settlement of overdue income tax refunds as one of the most important service delivery benchmarks against which the IRD should be assessed in 2027.
The department has been working to clear accumulated refund liabilities following the abolition of the Simplified Value Added Tax (SVAT) system and the introduction of a risk-based refund mechanism.
According to Wijewardena, the average time taken to process refunds has fallen to 29 days, compared with the statutory limit of 45 days. The department has also cleared Rs.7 billion in refund arrears dating back a decade.
The 2027 Budget seeks to further improve the refund mechanism by extending access to the fast-track VAT refund scheme to newly established export-oriented businesses recording at least 80% of their turnover from exports, after six months of registration.
It has also proposed granting legal recognition to electronic tax invoices as part of the broader effort to modernise tax administration and improve compliance.
The proposed changes reflect the Government’s wider effort to broaden the tax base, strengthen revenue collection and modernise the country’s tax administration. However, the effectiveness of the expanded capital gains tax framework will depend heavily on whether the IRD can establish transparent valuation standards and predictable rules for taxpayers and businesses.



Leave a comment