By The Pulseline News Desk
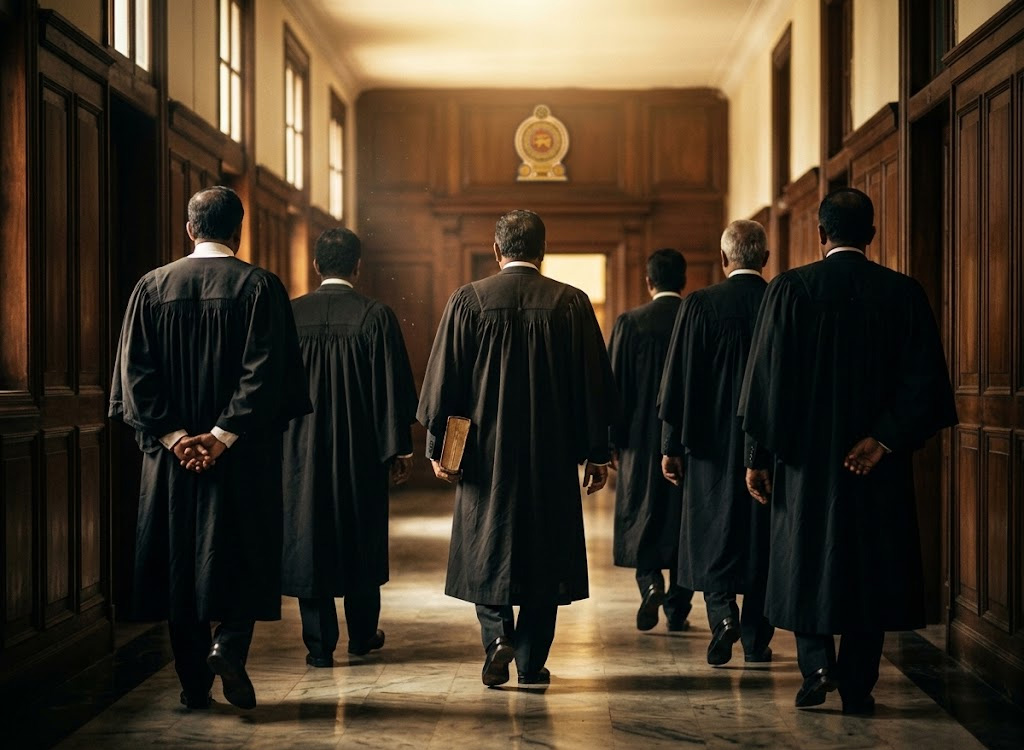
The country’s Supreme Court has dismissed three appeals challenging the taxation of judicial officers, ruling that judges serving in the High Court, District Courts, Magistrates’ Courts and Labour Tribunals are liable to income tax and that Advance Personal Income Tax (APIT) may be deducted from their remuneration.
The five-member Bench, comprising Chief Justice Preethi Padman Surasena and Justices Shiran Gooneratne, Janak De Silva, Mahinda Samayawardhana and Arjuna Obeyesekere, has dismissed the appeals without costs.
The ruling settles a dispute that had placed two constitutional principles against each other in the legal arguments: the State’s authority to impose generally applicable taxation and the constitutional independence and security of judicial officers.
Challenge to APIT
The appeals arose from a November 2, 2023, judgment of a Divisional Bench of the Court of Appeal, which had dismissed three writ applications filed by associations representing judicial officers.
Those associations represented High Court Judges, District Judges, Additional District Judges, Magistrates, Additional Magistrates and Presidents of Labour Tribunals.
The judicial officers had challenged the application of the Inland Revenue Act No. 24 of 2017, as amended, to their remuneration.
Their argument was not simply that judges should be exempt from taxation.
At the heart of their case was the contention that judicial officers do not occupy an ordinary employer-employee relationship with the State and therefore should not be treated as employees for taxation purposes.
They have also argued that judicial remuneration enjoys constitutional protection against reduction during a judge’s tenure.
Accordingly, they have contended that deducting APIT from their remuneration amounted, in effect, to reducing constitutionally protected remuneration.
The appellants had sought orders quashing the decision to subject judicial officers to APIT, preventing further deductions and requiring the repayment of amounts already deducted.
Supreme Court rejects constitutional challenge
Justice Janak De Silva, delivering the principal judgment, has held that applying the Inland Revenue Act to the judicial officers concerned did not violate the Constitution.
A significant aspect of the ruling was the Court’s consideration of the argument that treating judges as “employees” for taxation purposes could compromise judicial independence.
Justice De Silva has held that the Inland Revenue Act did not create an employer-employee relationship between judicial officers and the relevant State authorities.
Instead, the legislation recognised, for taxation purposes, the factual role played by the Secretary to the relevant Ministry in paying judicial officers’ salaries and identifying the person responsible for deducting APIT.
This distinction was central to the Court’s reasoning.
In other words, the tax legislation’s treatment of judicial officers for the purpose of collecting income tax did not, by itself, transform the constitutional relationship between the judiciary and the Executive into an ordinary employment relationship.
Judicial independence and taxation
The judgment has also addressed the broader constitutional question of whether taxation could interfere with judicial independence.
Justice De Silva has acknowledged judicial independence as a foundational constitutional principle.
However, he has held that judicial officers remain subject to taxation imposed by law when the tax is of general application, non-discriminatory and not specifically directed at judges or the judiciary.
The ruling therefore distinguishes between a tax imposed generally across society and a measure specifically designed to affect judicial remuneration.
The former, according to the judgment, does not become unconstitutional merely because judicial officers are among those required to pay it.
APIT is advance collection of tax
The respondents had argued that APIT does not constitute a separate tax imposed on judicial officers but is instead a mechanism for collecting income tax in advance.
The State has maintained that judicial officers were liable to income tax under the Inland Revenue Act in the same manner as other persons falling within the statutory tax framework.
The respondents have further argued that applying the tax to judicial officers was neither discriminatory nor an interference with judicial independence.
The Supreme Court has ultimately accepted the position that judicial officers are liable to income tax and that APIT deductions could lawfully be made from their remuneration.
Different constitutional reasoning
While the five judges had agreed on the outcome, the judgment has also contained an important judicial difference in reasoning.
Justice Shiran Gooneratne has agreed with the conclusions concerning the income tax liability of judicial officers and the operation of APIT, but has expressed a different view on certain aspects of the constitutional reasoning.
The distinction is significant because the judgment deals with questions extending beyond tax administration to the constitutional relationship between the judiciary and the State.
A wider constitutional question
The case ultimately goes beyond the issue of deductions appearing on judges’ pay slips.
It raises a broader question: where does constitutional protection of judicial remuneration end and the State’s general power to tax begin?
The Supreme Court’s answer is that judicial independence does not, by itself, create an exemption from a generally applicable tax law.
The decisive considerations include whether the tax is imposed through legislation of general application, whether it operates without discrimination and whether it specifically targets the judiciary.
The ruling therefore establishes that judicial officers cannot claim immunity from generally applicable income taxation solely on the basis of judicial independence.
For the State, the decision provides judicial confirmation of its authority to apply the Inland Revenue Act and APIT framework to judicial officers.
For the judiciary, the judgment clarifies that constitutional protection of judicial independence remains distinct from exemption from generally applicable taxation.



Leave a comment