By The Pulseline News Desk
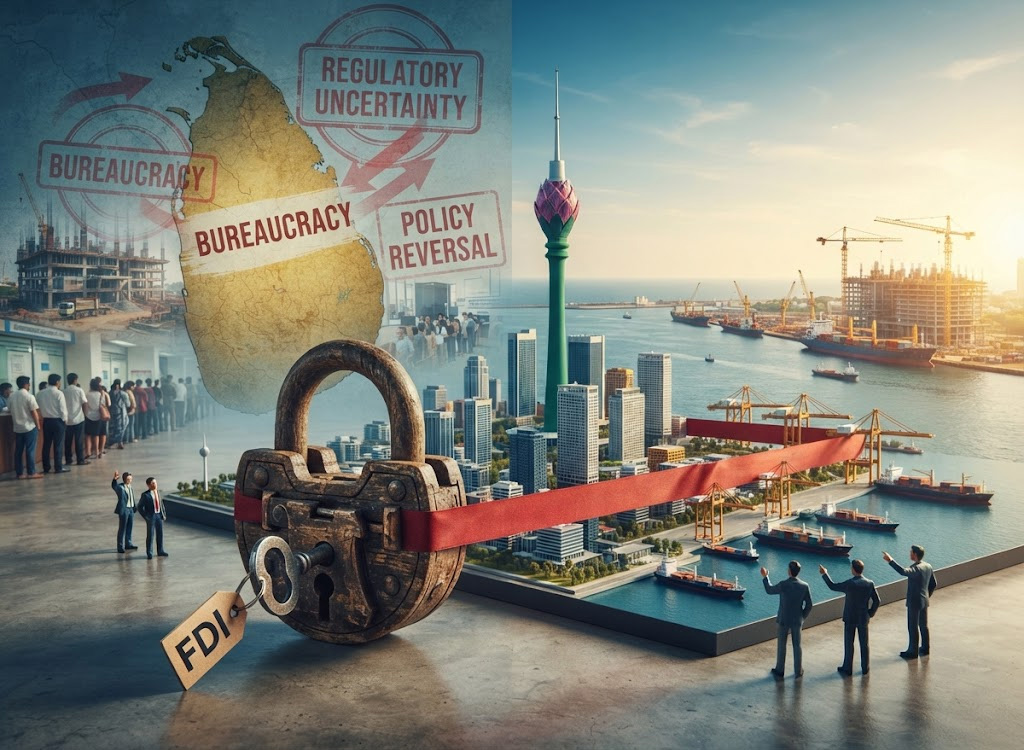
Sri Lanka’s economic recovery may be gathering momentum, but attracting the foreign investment needed to sustain that recovery remains a challenge, with investors continuing to point to regulatory uncertainty, bureaucracy and policy reversals as major obstacles.
The warning comes in the 2026 Sri Lanka Investment Climate Statement by the United States (US) Department of State, which acknowledges stronger economic growth and greater political stability while highlighting persistent structural weaknesses in the country’s investment environment.
Sri Lanka recorded 5% GDP growth in 2025, exceeding expectations and strengthening the post-crisis recovery. The political transition following the election of President Anura Kumara Dissanayake and the National People’s Power (NPP), together with the Government’s continued commitment to the US$3 billion IMF programme, has also provided some reassurance to investors.
But the recovery has yet to translate into a major increase in foreign direct investment.
FDI remains below potential
Sri Lanka attracted US$1.06 billion in FDI in 2025, equivalent to around 1% of GDP.
The US assessment notes that this remains well below the 3–4% of GDP commonly recorded by emerging economies, highlighting the scale of the gap between Sri Lanka’s investment ambitions and actual inflows.
Manufacturing, port development, tourism, information technology and business process outsourcing, and real estate were among the main sectors attracting foreign capital.
Investment experts cited in the assessment point to several areas that need attention if Sri Lanka is to substantially increase FDI — including policy stability, regulatory reform, skilled labour, industrial land, logistics and trade facilitation.
Preferential access to export markets through Free Trade Agreements (FTAs) is also identified as an important factor in investment decisions, particularly for manufacturers that depend on imported raw materials and intermediate goods.
Policy uncertainty remains a concern
One of the central issues identified by the assessment is not the absence of investment opportunities, but uncertainty over the rules under which investors will operate.
Foreign companies have raised concerns over project reversals, regulatory changes, slow government decision-making, high transaction costs and inadequate support for existing investments.
The Board of Investment (BOI), which is expected to function as the country’s main investment promotion agency, also faces limitations because decision-making powers remain spread across several government institutions.
That fragmentation can turn the much-promoted concept of a “one-stop shop” into a lengthy approval process.
The BOI has nevertheless taken steps towards digitalisation, including the launch of its Ready to Invest platform in May 2026, providing sector-specific investment opportunities.
Big projects, big questions
Several major investment projects illustrate the opportunities — as well as the uncertainty — surrounding Sri Lanka’s investment strategy.
Among them is the proposed US$3.7 billion Sinopec oil refinery project near Hambantota International Port, which President Dissanayake committed to finalising in January 2025.
The project could potentially become the largest FDI project in Sri Lanka’s history. However, the assessment says it remained pending as of June 2026 amid disagreements between the Government and Sinopec.
Another major development was the withdrawal by India’s Adani Green Energy in February 2025 from a proposed US$400 million, 484 MW wind power project in northern Sri Lanka following Government efforts to renegotiate the previously awarded contract.
The Government also ended negotiations with China Harbour Engineering Company over a proposed floating LNG terminal and halted plans to privatise several state-owned enterprises, opting instead for restructuring while retaining state ownership.
For investors, such developments can have implications beyond individual projects, particularly when assessing the predictability of long-term investment decisions.
The contradiction at the heart of the investment strategy
Sri Lanka offers considerable incentives for foreign investors.
The country permits 100% foreign ownership in most economic sectors, while providing constitutional protection for investments and allowing the repatriation of earnings, fees and capital.
Yet significant restrictions remain in sectors ranging from banking, aviation and coastal shipping to agriculture, mining, communications and certain services.
Foreign ownership exceeding 40% has historically required approval in a number of sectors, while foreign investment is prohibited altogether in activities such as coastal fishing, money lending, pawnbroking and retail businesses with capital investment below US$5 million.
Land ownership is another major constraint, with restrictions generally preventing foreigners and companies with more than 50% foreign equity from owning land, subject to exemptions.
The result is an investment regime that is formally open in many areas but still contains a considerable number of regulatory and administrative barriers.
Trade access could become decisive
The investment climate is also closely linked to Sri Lanka’s trade ambitions.
Sri Lanka has bilateral FTAs with India, Pakistan, Singapore and Thailand, while also benefiting from the European Union’s GSP+ arrangement and participating in several regional and multilateral trade frameworks.
The country has also expressed its intention to join the Regional Comprehensive Economic Partnership (RCEP) and is progressing through the formal accession process.
For export-oriented investors, improved access to major markets could make Sri Lanka more attractive as a manufacturing and services base.
But the assessment says trade facilitation itself remains a weakness, with import licensing, duties and para-tariffs, complex labour rules and manual administrative processes continuing to increase the cost of doing business.
Digital economy, but manual bureaucracy
Despite repeated calls for digitalisation, manual procedures remain at key institutions including Sri Lanka Customs, the Sri Lanka Ports Authority and the BOI.
The report also identifies weak contract enforcement and court backlogs as significant concerns for businesses seeking predictable dispute resolution.
For a country attempting to position itself as a regional investment and logistics hub, these administrative delays can become more than a bureaucratic inconvenience. They can directly affect project costs, delivery schedules and investor confidence.
Port City and new investment zones
The Government is also seeking to develop new platforms for investment.
Sri Lanka currently has 18 Export Processing Zones administered by the BOI, where foreign investors receive treatment equivalent to local investors.
The Colombo Port City Special Economic Zone, built on 665 acres of reclaimed land near Colombo Port, remains another major component of the country’s investment strategy.
The Government intends to review the Port City legislative framework to improve its attractiveness to investors, while amendments introduced in January 2026 have limited tax holidays, harmonised employee taxation and strengthened regulatory oversight.
A separate 400-acre pharmaceutical manufacturing zone in Hambantota is being developed with the stated objective of meeting 40% of Sri Lanka’s pharmaceutical requirements and generating as much as US$1 billion in annual exports.
Stronger banks, stronger reserves
The investment climate assessment also records improvements in several areas of the economy.
Sri Lanka’s banking sector recorded a 19% increase in after-tax profits in 2025, reaching approximately US$1.2 billion, while total banking assets increased 12% to around US$80 billion.
The banking system maintained capital above minimum regulatory requirements, with the total Capital Adequacy Ratio at 18% at the end of 2025.
Meanwhile, the Central Bank purchased US$2 billion in foreign exchange during 2025, helping gross official reserves rise to US$6.8 billion, their highest level since the 2022 crisis.
Workers’ remittances also reached a record US$8.1 billion, up from an estimated US$6.6 billion in 2024.
These developments strengthen the broader macroeconomic backdrop for investment, but the assessment suggests that macroeconomic stabilisation alone will not be enough to generate a sustained FDI surge.
SOE and corruption problem
Sri Lanka’s state-owned enterprise (SOE) sector remains another major challenge.
The Government controls 527 SOEs, including 55 classified as strategically important.
The assessment identifies mismanagement, excessive staffing, inadequate financial disclosure and weak budgetary controls as continuing problems.
While the previous administration pursued potential privatisation of major SOEs, the current Government has suspended those efforts and instead opted for restructuring while retaining state ownership.
Corruption and a lack of transparency in public procurement are also cited as longstanding obstacles to attracting foreign investment.
Although President Dissanayake has publicly committed to tackling corruption and improving transparency, stakeholders continue to raise concerns over corruption risks and politically connected interests in some sectors.
Sri Lanka’s human capital problem
Perhaps one of the less visible constraints on investment that is becoming increasingly important is the availability of skilled workers.
The assessment describes skilled labour shortages as a critical operational challenge, particularly after significant emigration from tourism, apparel, IT and engineering.
Sri Lanka’s employed workforce stood at around 8.1 million in 2025, with services accounting for 50.6%, industry 26.3% and agriculture 23.2%.
While labour costs remain relatively low compared with developed economies, they are generally higher than in some competing South Asian countries, while businesses continue to report shortages of specialised technical skills.
The problem is particularly visible in sectors such as construction, manufacturing and plantation agriculture. The garment industry, for example, reportedly experiences annual employee turnover of as much as 40%.
More than 310,000 Sri Lankans registered for overseas employment in 2025, further contributing to the shortage of skilled workers at home.
Recovery is only the first step
Sri Lanka has emerged from one of the most severe economic crises in its modern history with stronger growth, higher reserves, record remittances and a more stable macroeconomic environment.
But the latest investment climate assessment points to a second, more difficult phase of recovery.
The challenge is no longer simply stabilising the economy. It is creating an investment environment in which international companies can make long-term decisions with confidence.
That will require more than announcing large projects or offering investment incentives.
For Sri Lanka to move FDI from around 1% of GDP towards the levels seen in other emerging economies, the assessment points towards a combination of predictable policies, faster approvals, stronger governance, improved trade facilitation, digitalised public services, better contract enforcement and a deeper pool of skilled labour.
The message from the assessment is therefore straightforward: Sri Lanka has the economic foundations and investment opportunities, but converting those opportunities into sustained foreign capital will depend heavily on how predictable and efficient the investment environment becomes.



Leave a comment